The insurance company offered $902. We got the roof approved at $279,824.
A 107-square cedar shake roof, a $13,465 deductible, and a claim that was closed twice before it was paid. This is every step we took, with the photos we sent the insurance company.
- Roof
- Cedar shake, house + garage
- Size
- 107 squares, 10/12 to 12/12
- Claim
- Windstorm, Oct 2025
- First contact to approval
- 7½ months
Approved replacement cost
$279,824
107 squares · about $2,615 per square
How it went, in order
Most homeowners only see the first letter and the last check. Here's everything in between.
01 · January 2026
The first look
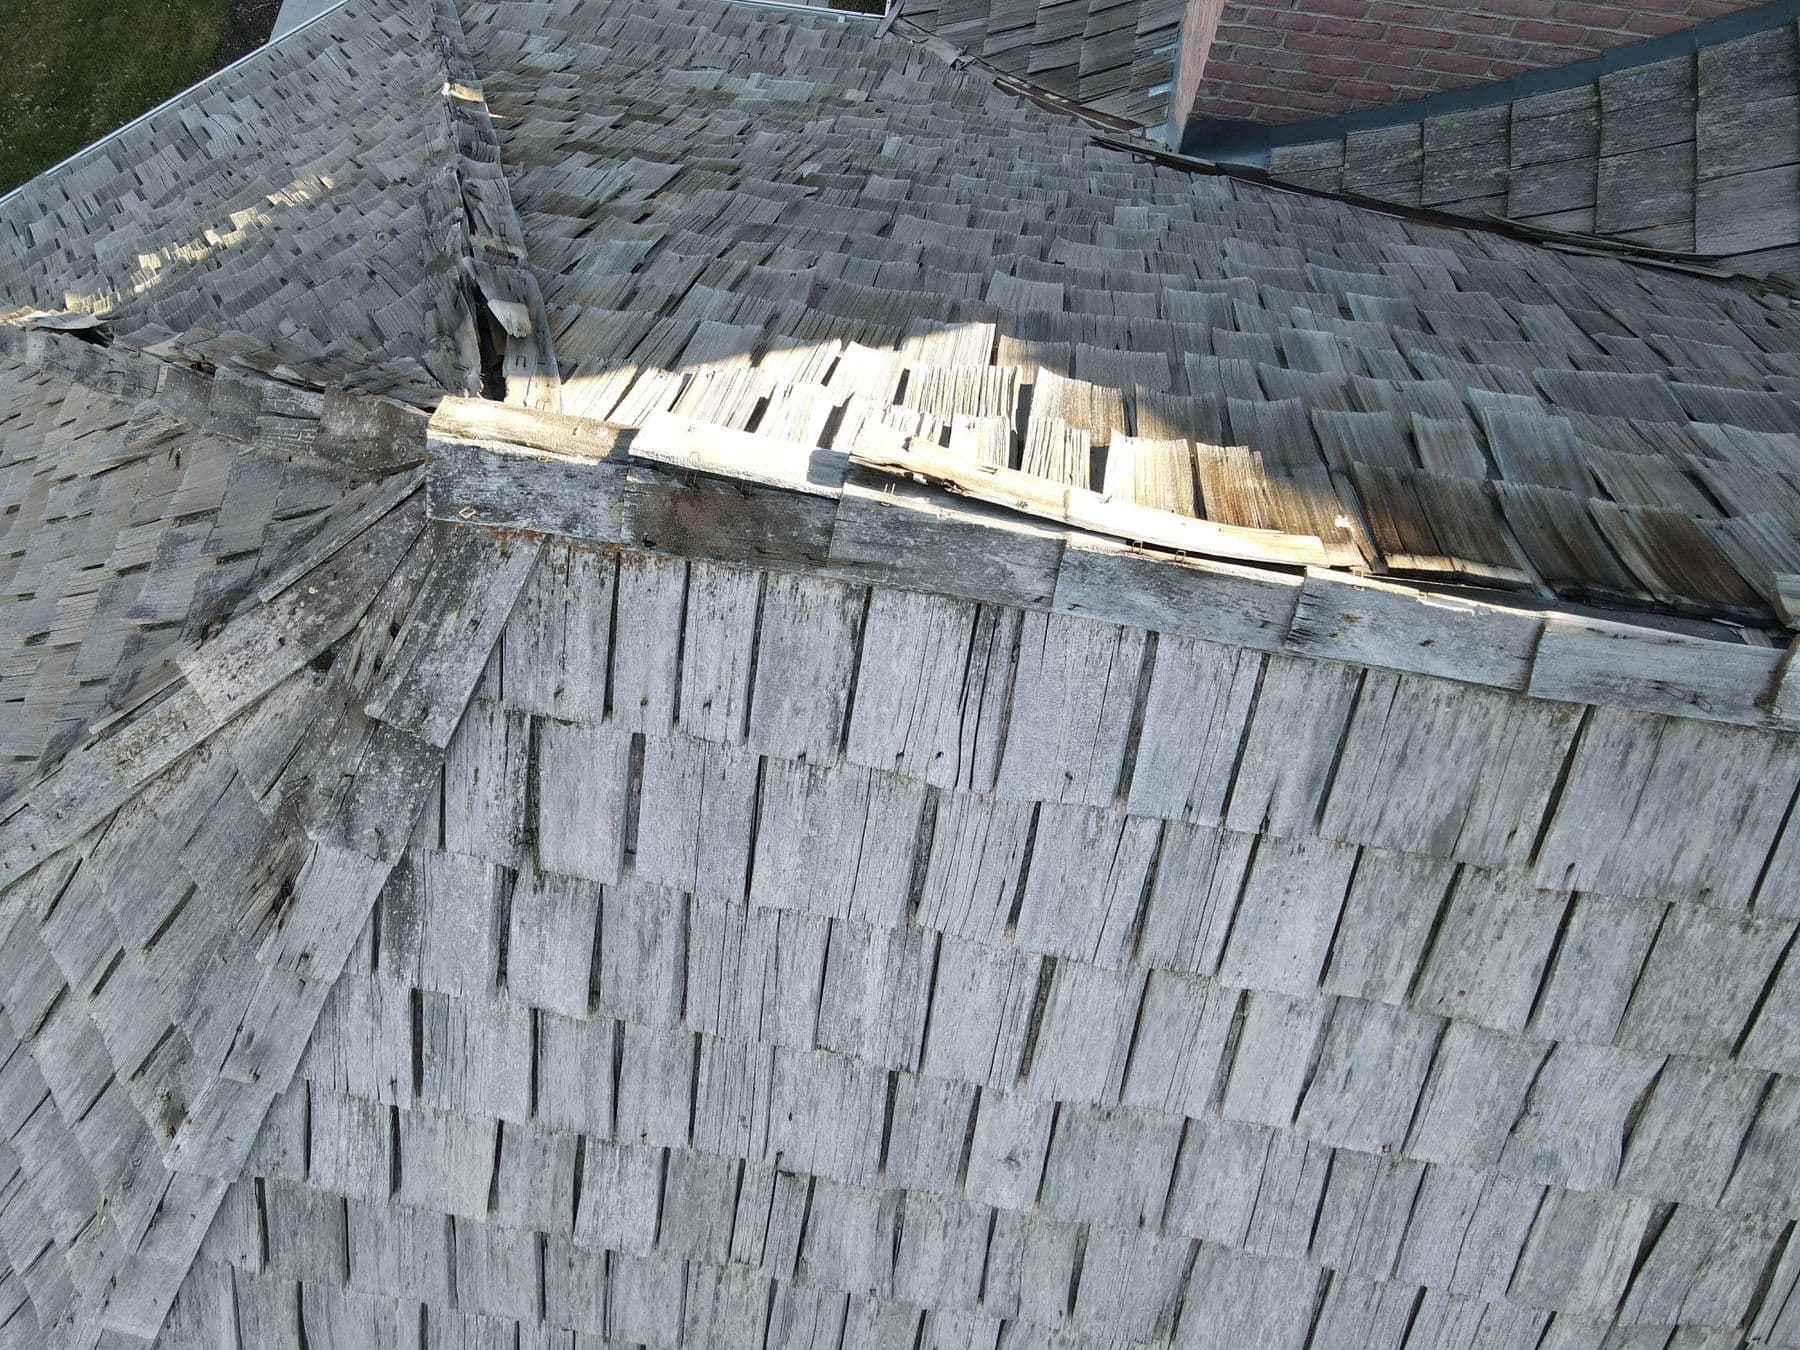
A windstorm hit Provo on October 11, 2025, with gusts recorded around 45 mph at the house. When our rep knocked in January, the damage was easy to see from a drone: ridge caps lifted and split, and shakes missing on the slopes below them.
We filed the claim with the homeowner, sent the insurance company our photo report, and the adjuster inspected the roof on January 20.
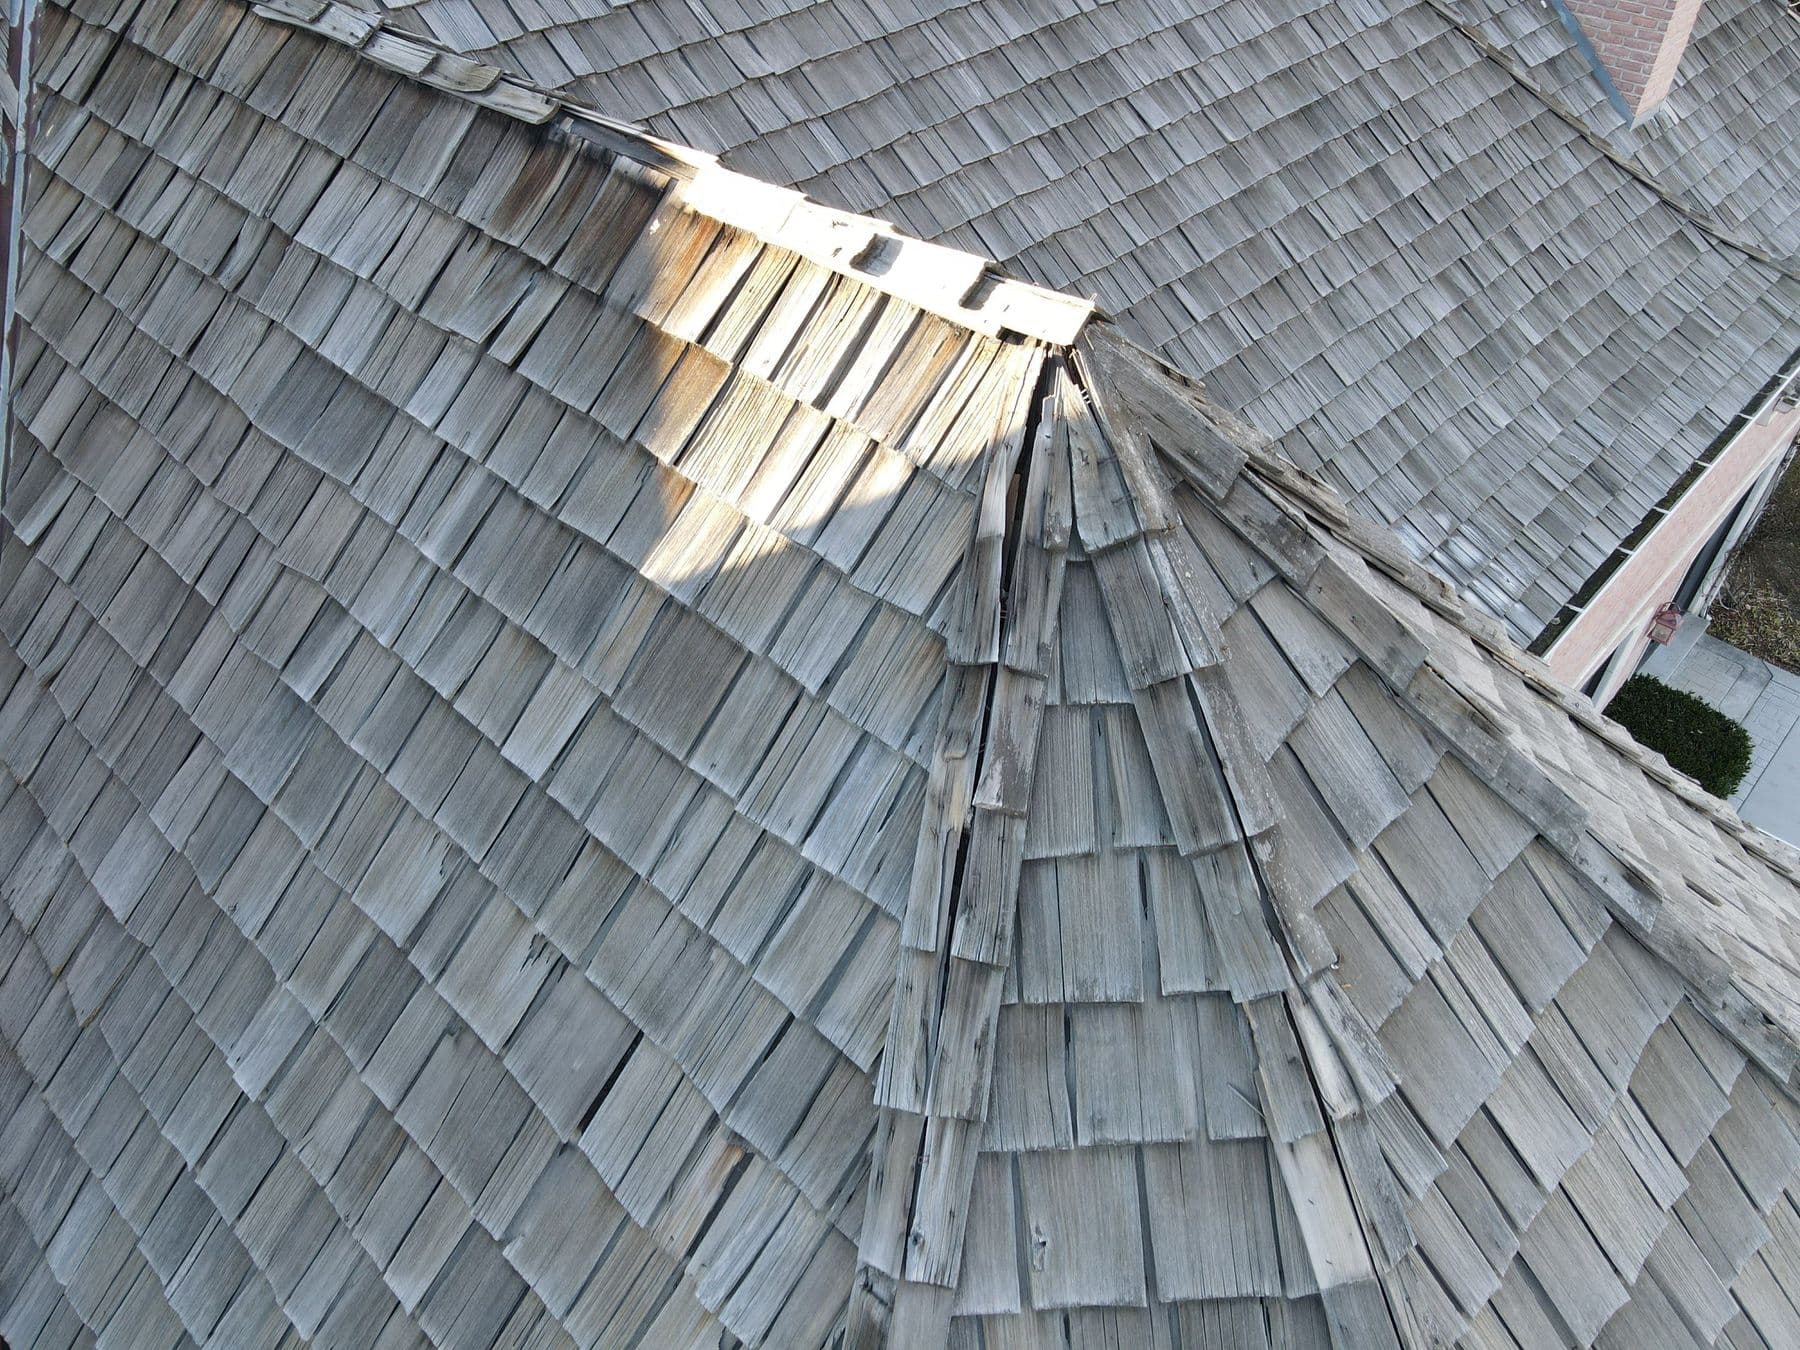
A hip cap split open at the peak 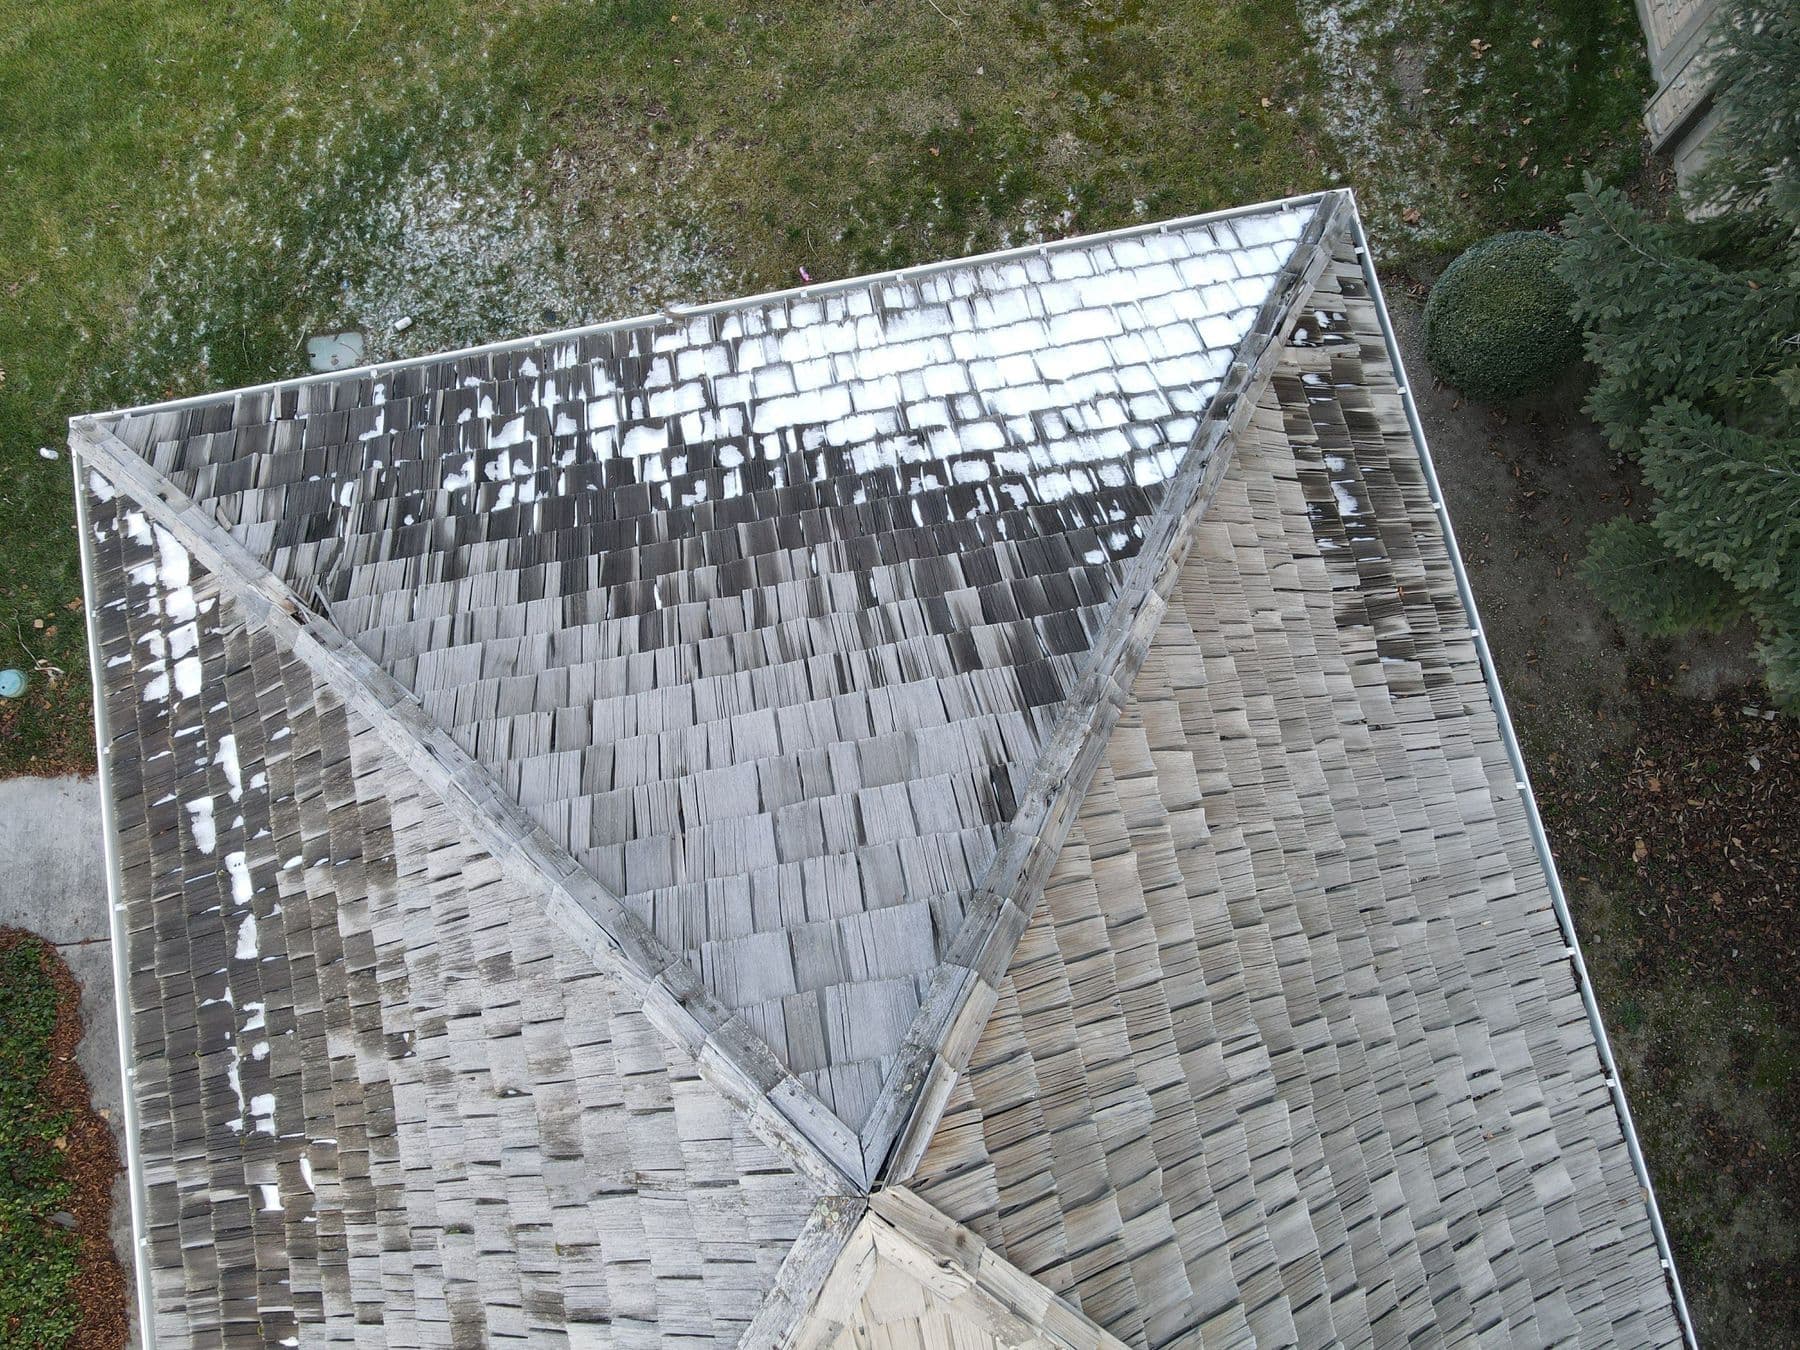
The roof from the air, January 02 · January 26
The first estimate: $902.72
The insurance company's estimate paid for 35 feet of ridge cap and three hours of labor. Against a $13,465 deductible, the homeowner's payment came to $0. The claim was written up as a loss below deductible.
Deductible $13,465Jan 26First estimate
$902.72
35 LF of hip and ridge cap plus 3 hours of labor. Payment: $0.
Apr 10Revised for 50 shakes
under $13,465
Added 50 replacement shakes. Still below the deductible. Payment: $0.
SepFinal approval, full replacement
$279,824.00
Full cedar replacement on the house and garage, code upgrades included.
03 · February
We asked to test it, and the first test held
Cedar shake gets brittle with age. If you can't replace a damaged shake without breaking the ones around it, the roof can't be repaired, and a repair estimate means nothing. So we asked the insurance company whether it would accept a repairability test done to HAAG engineering guidelines. It said yes and asked for video.
Our first test held up. Honestly, for about a month this file was headed toward “the homeowner pays out of pocket.” Then the rep who sold the job went back and looked again.
04 · March 26 to April 1
Every slope, numbered. Every shake, circled.
We flew the whole roof again and broke it into 19 numbered slopes. On each one we circled every missing or damaged shake and counted them. The insurance company had said the slopes had no damage.
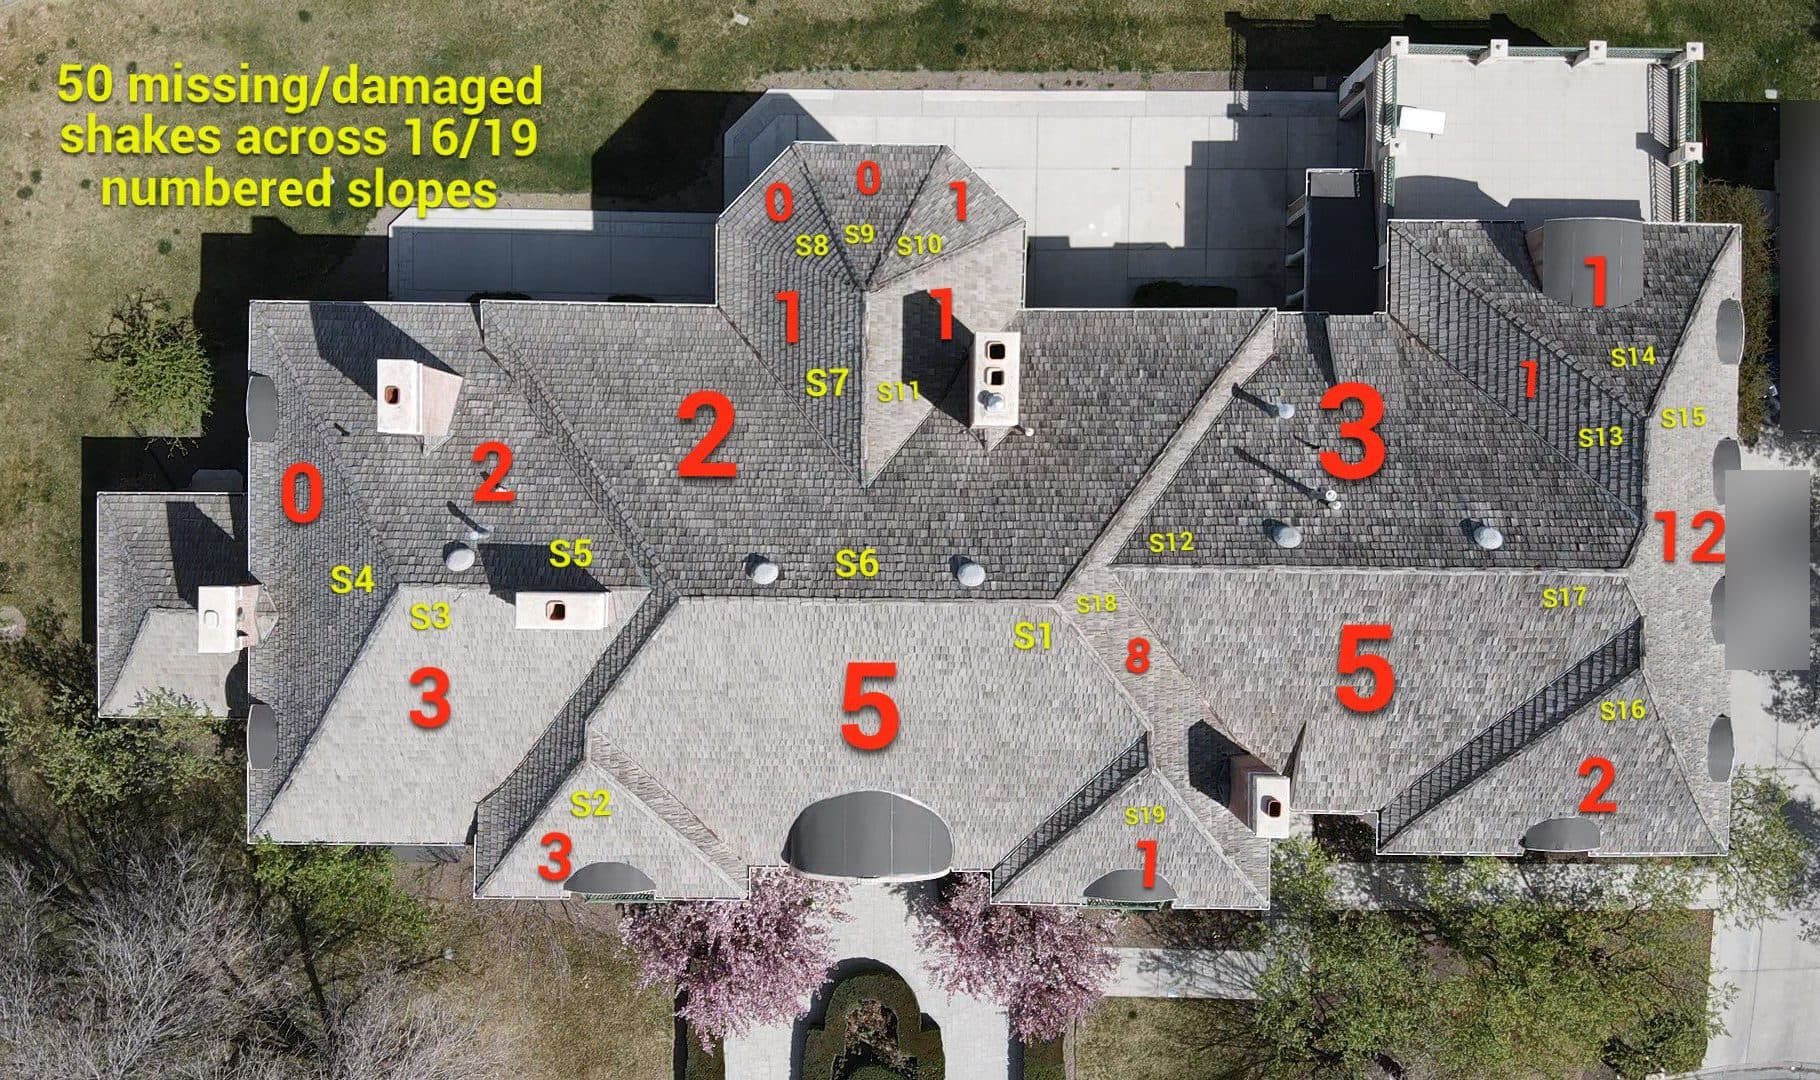
50
missing or damaged shakes
16 of 19
slopes with damage
12
on the worst slope
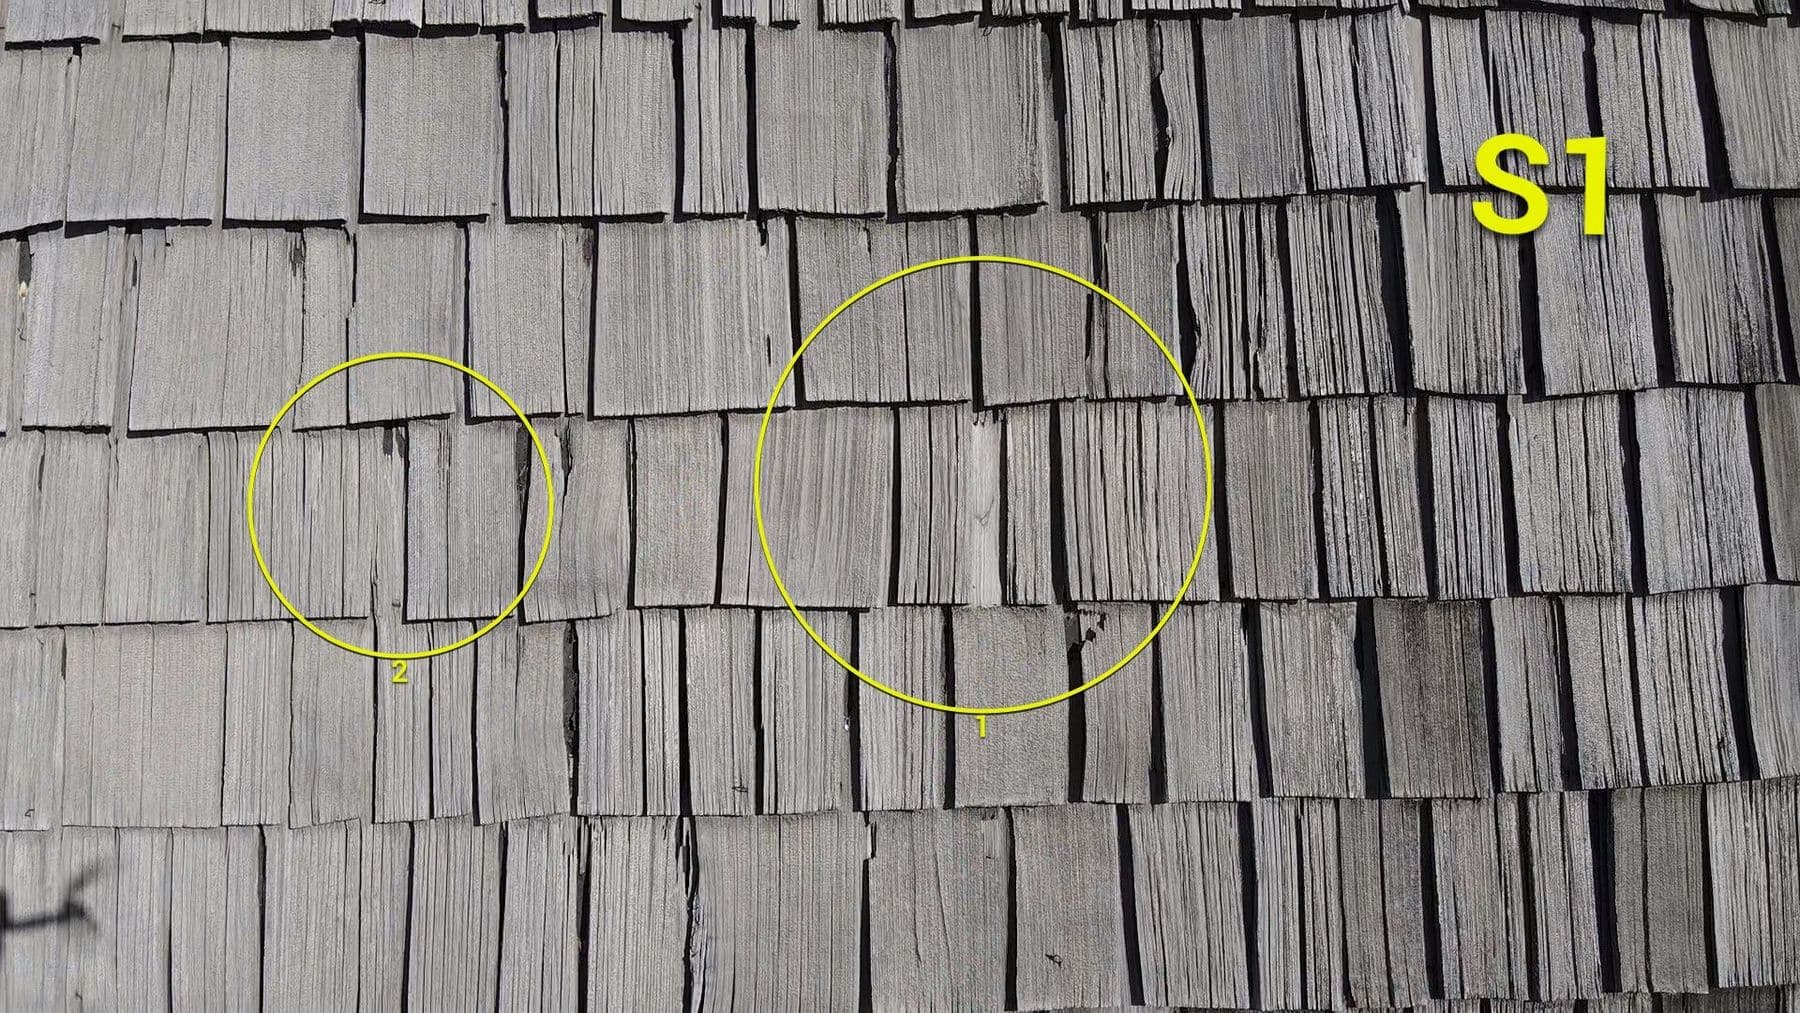
Slope S1: five or more damaged shakes 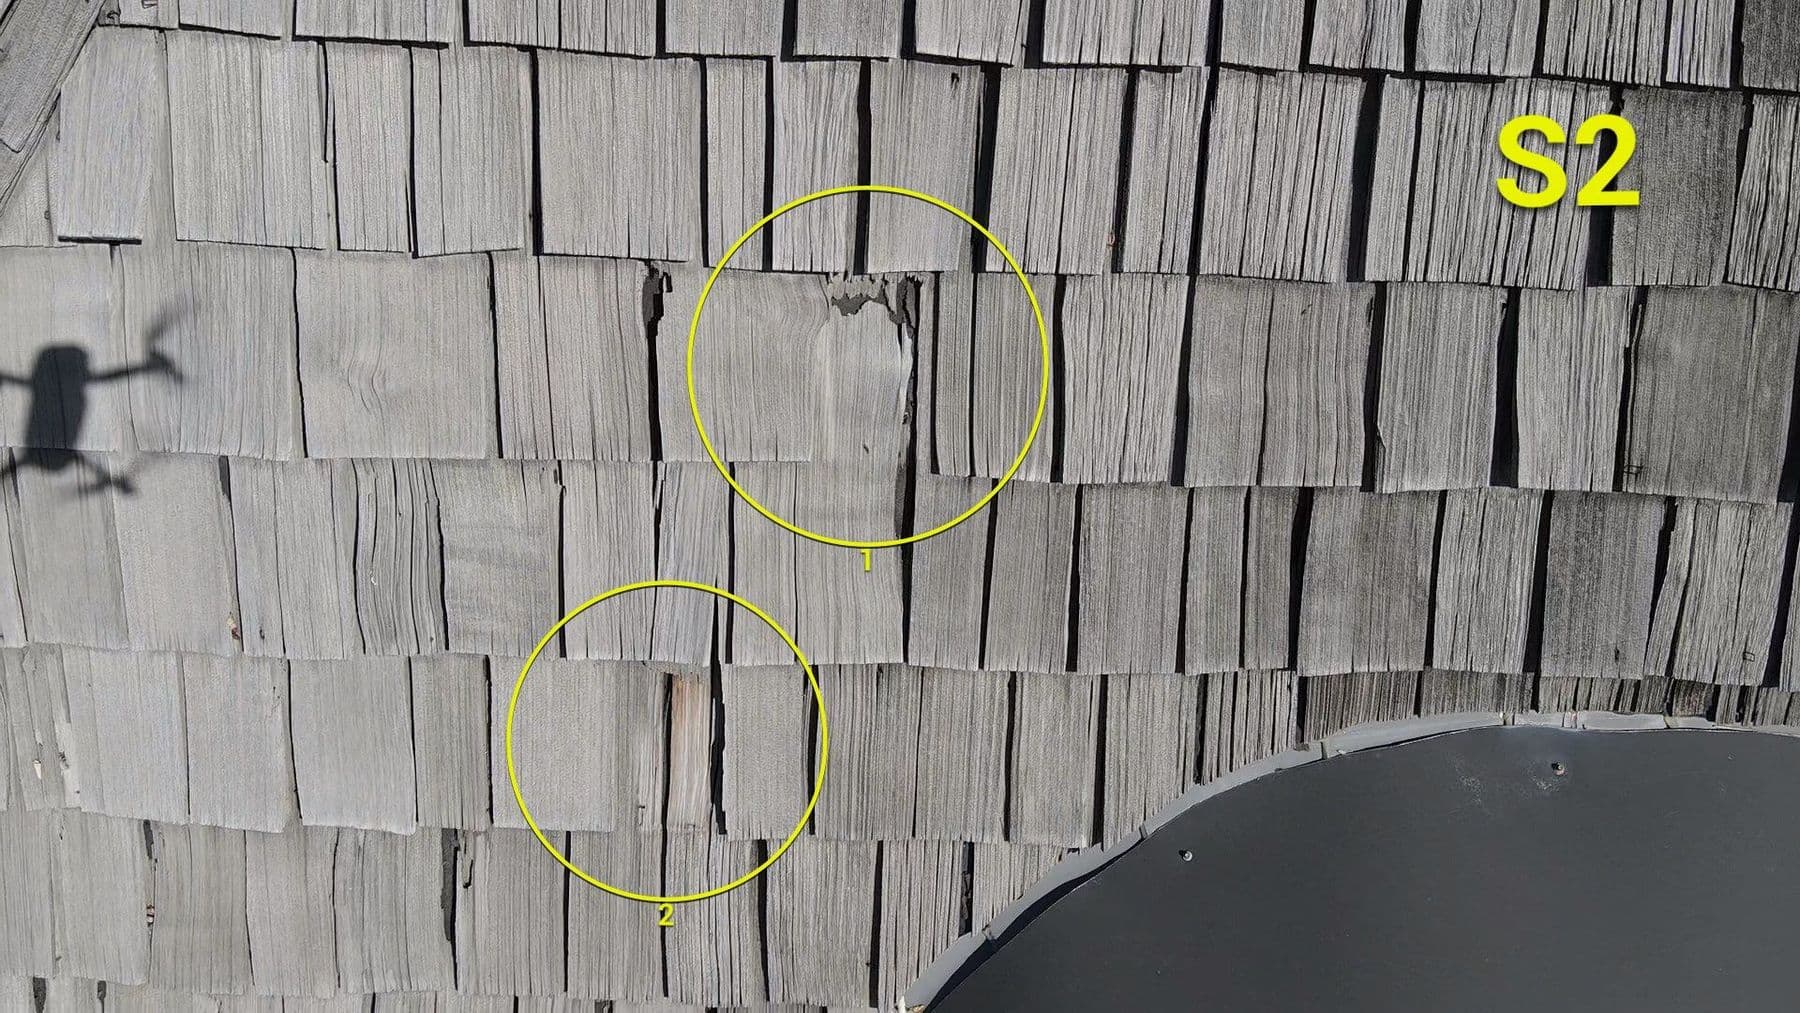
Slope S2: split and missing shakes 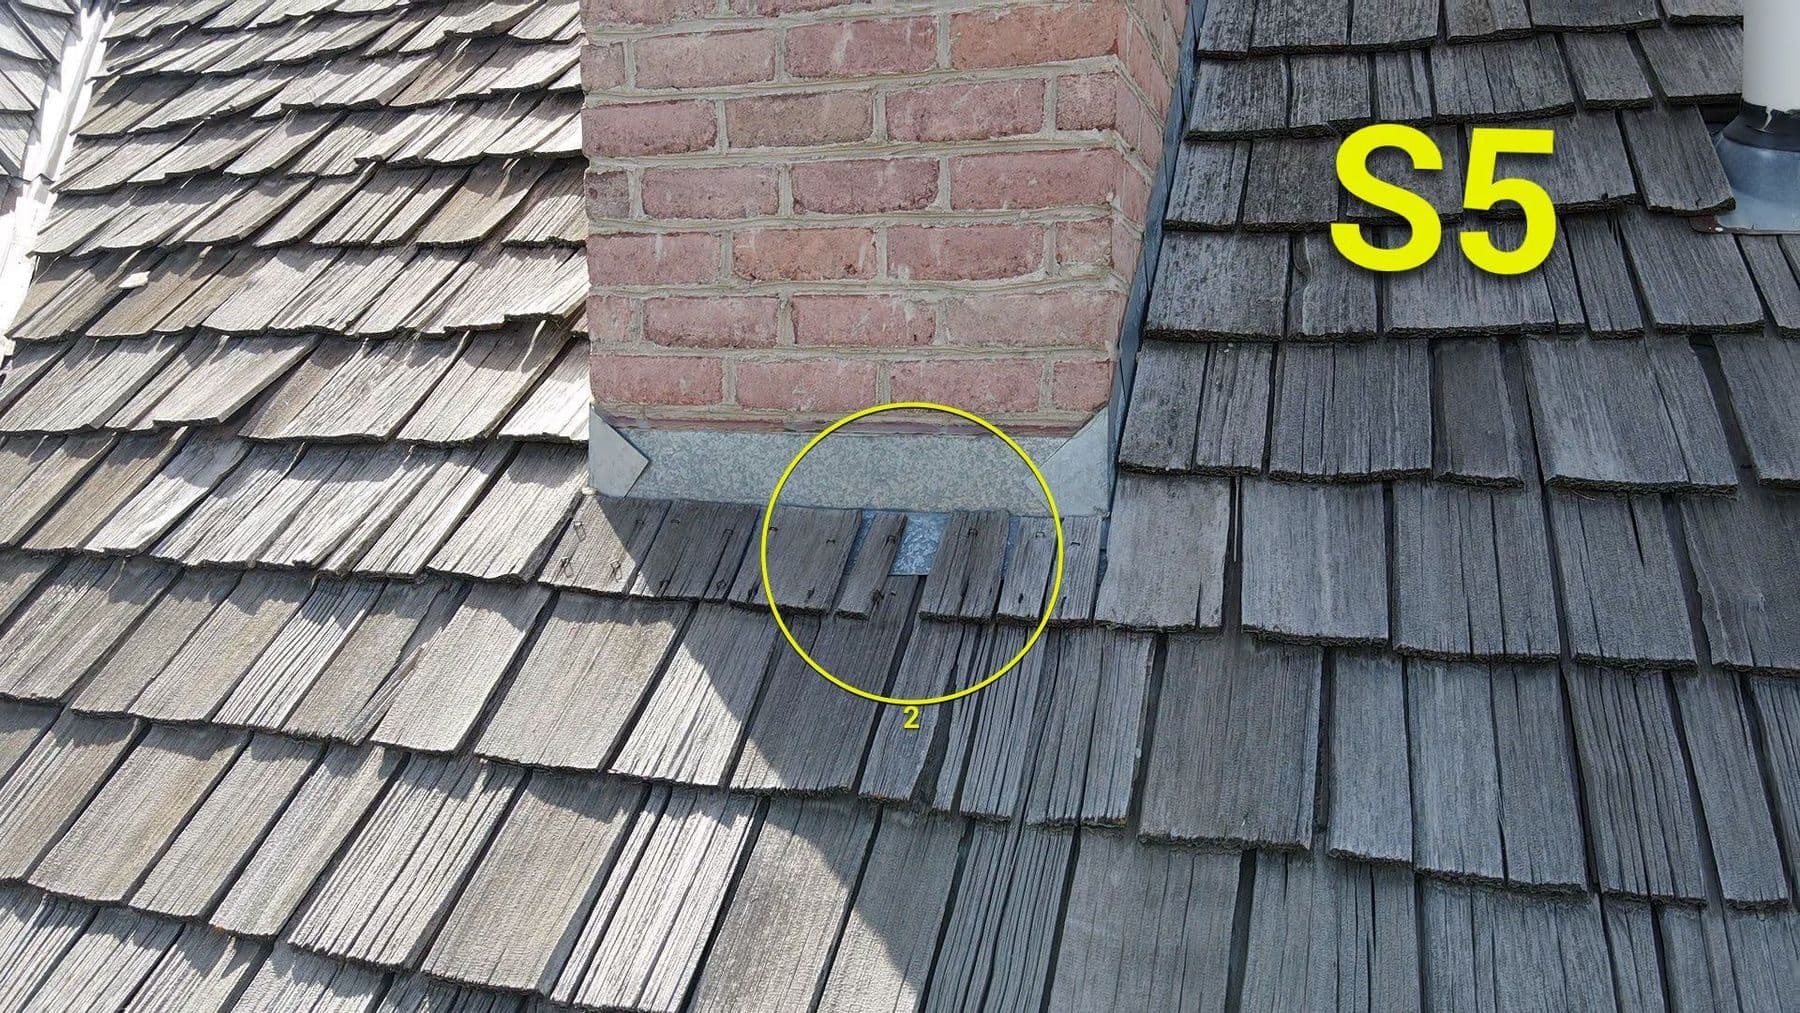
Slope S5: at the chimney 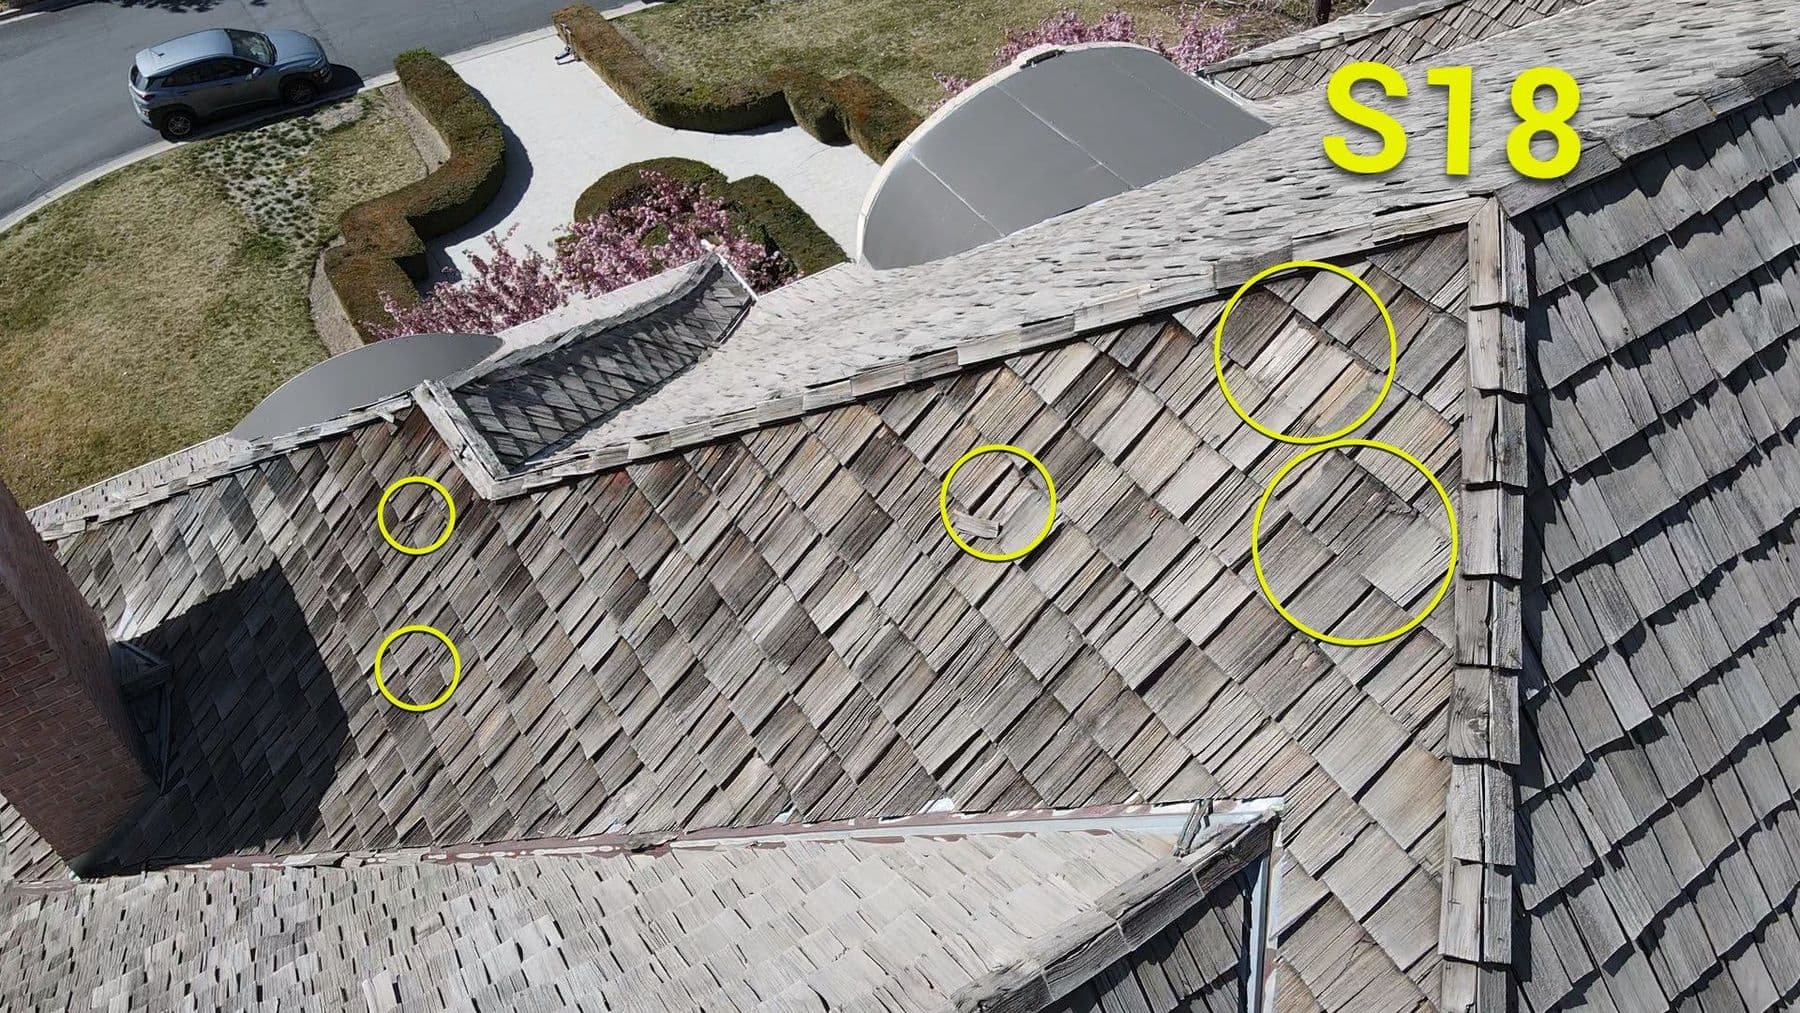
Slope S18: eight damaged shakes 05 · April 2 to 13
Revised, and still $0
We sent the new photo report and asked for a re-inspection. The insurance company told us only the policyholder could request one, so we walked the homeowner through making that request. Then came the answer:
Robinhood · Apr 2
We attached a photo report highlighting storm damage and missing shakes. Could we schedule a re-inspection?
Insurance company · Apr 10
The estimate was revised to include the replacement of 50 wood shakes, in which the claim is still a loss below deductible. No re-inspection is warranted at this time.
Robinhood · Apr 13
Thank you. Would you be alright with us performing a repair test on the slopes and sending it for you to review?
That April answer ended up mattering more than anything else. By paying for 50 shakes, the insurance company had put in writing that the slopes were damaged.
06 · May 19
Repair test #2, on a slope
Our claims lead went up with new cedar and filmed the whole thing, about 12 minutes: pulling one damaged shake and sliding in a new one, the same way any repair crew would. The shake above it cracked. Then the course above that one cracked too.
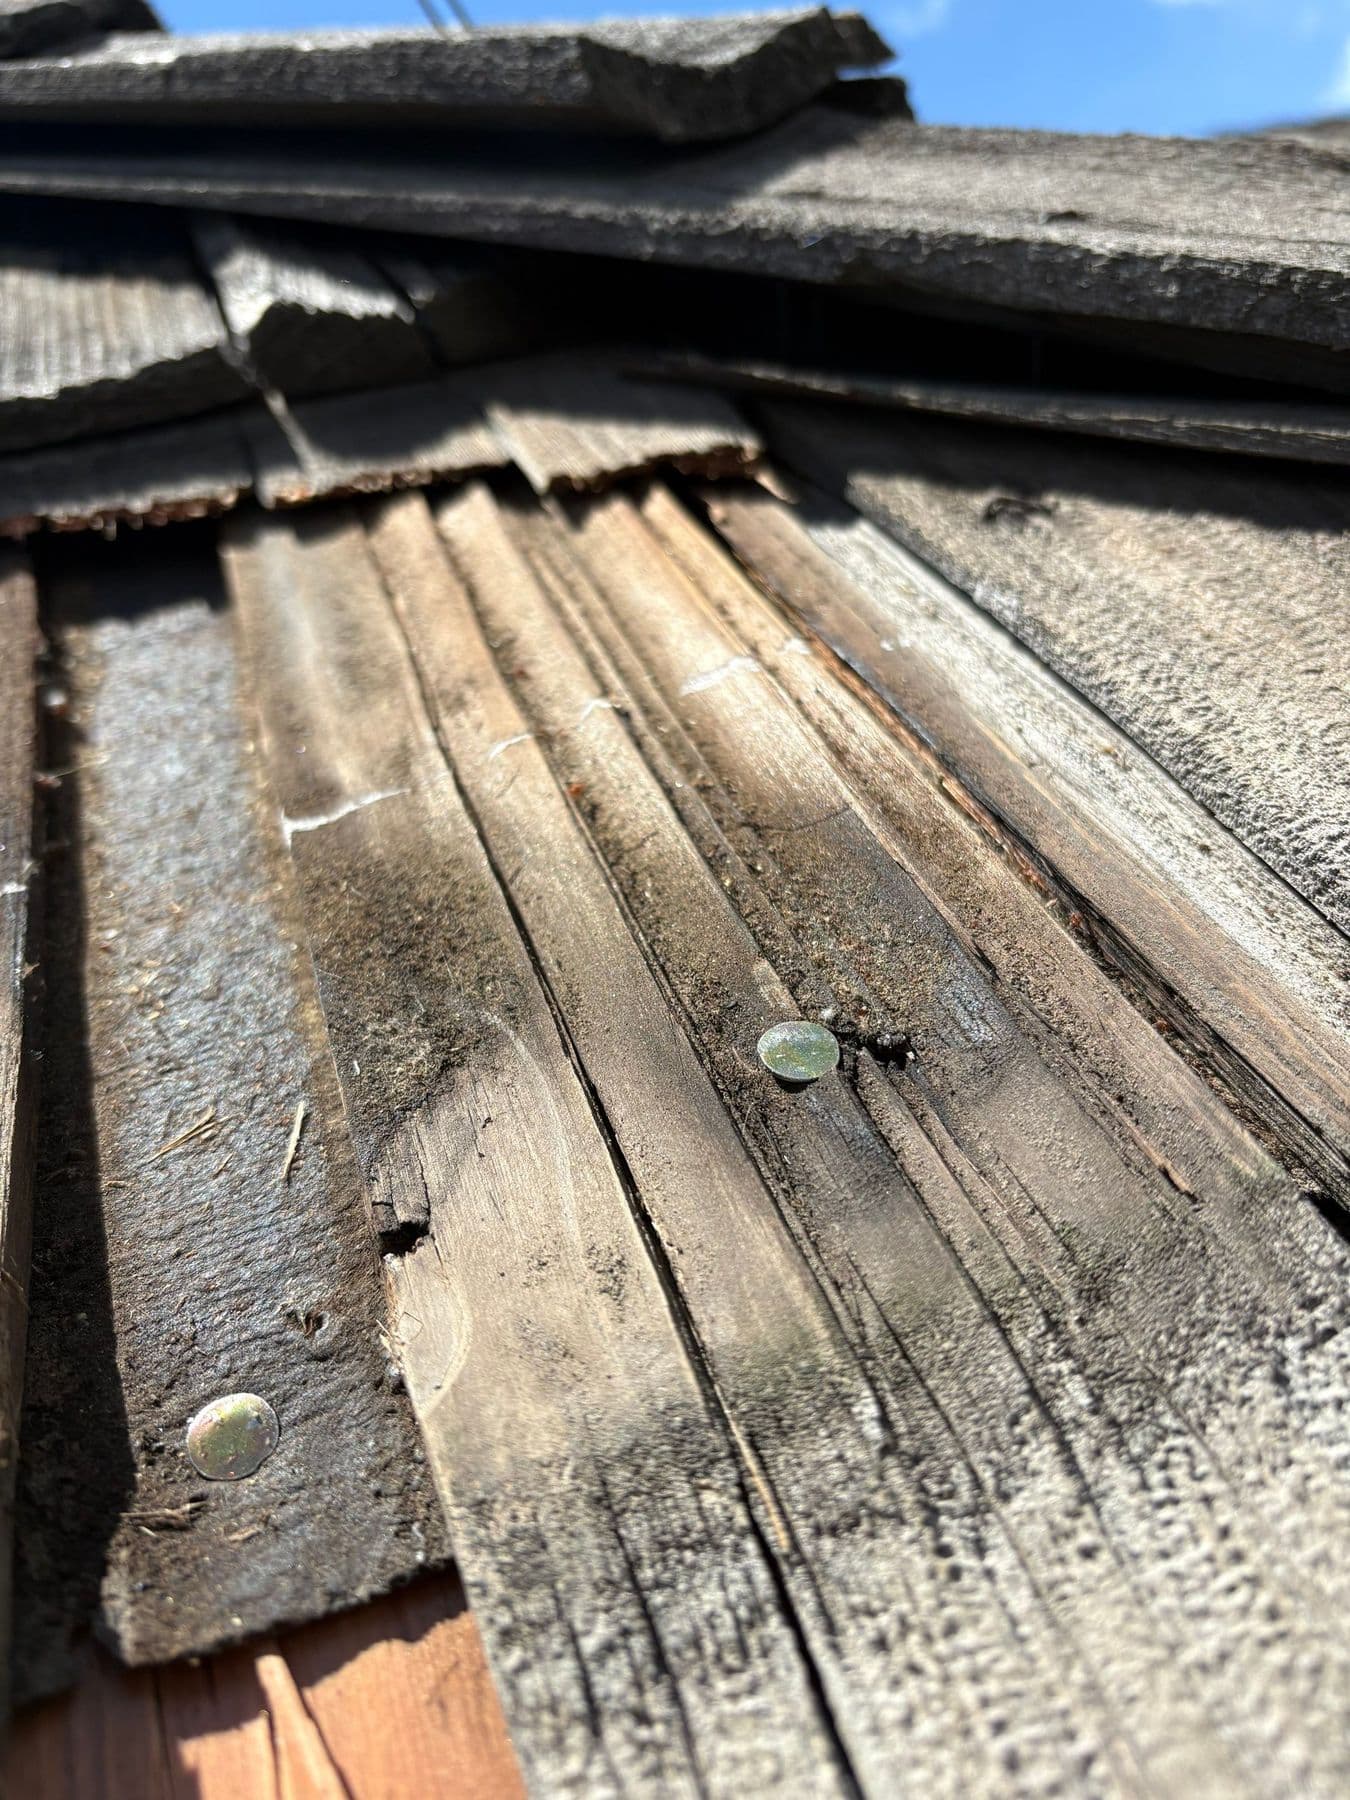
Prying up one shake exposes nails set in brittle, split wood 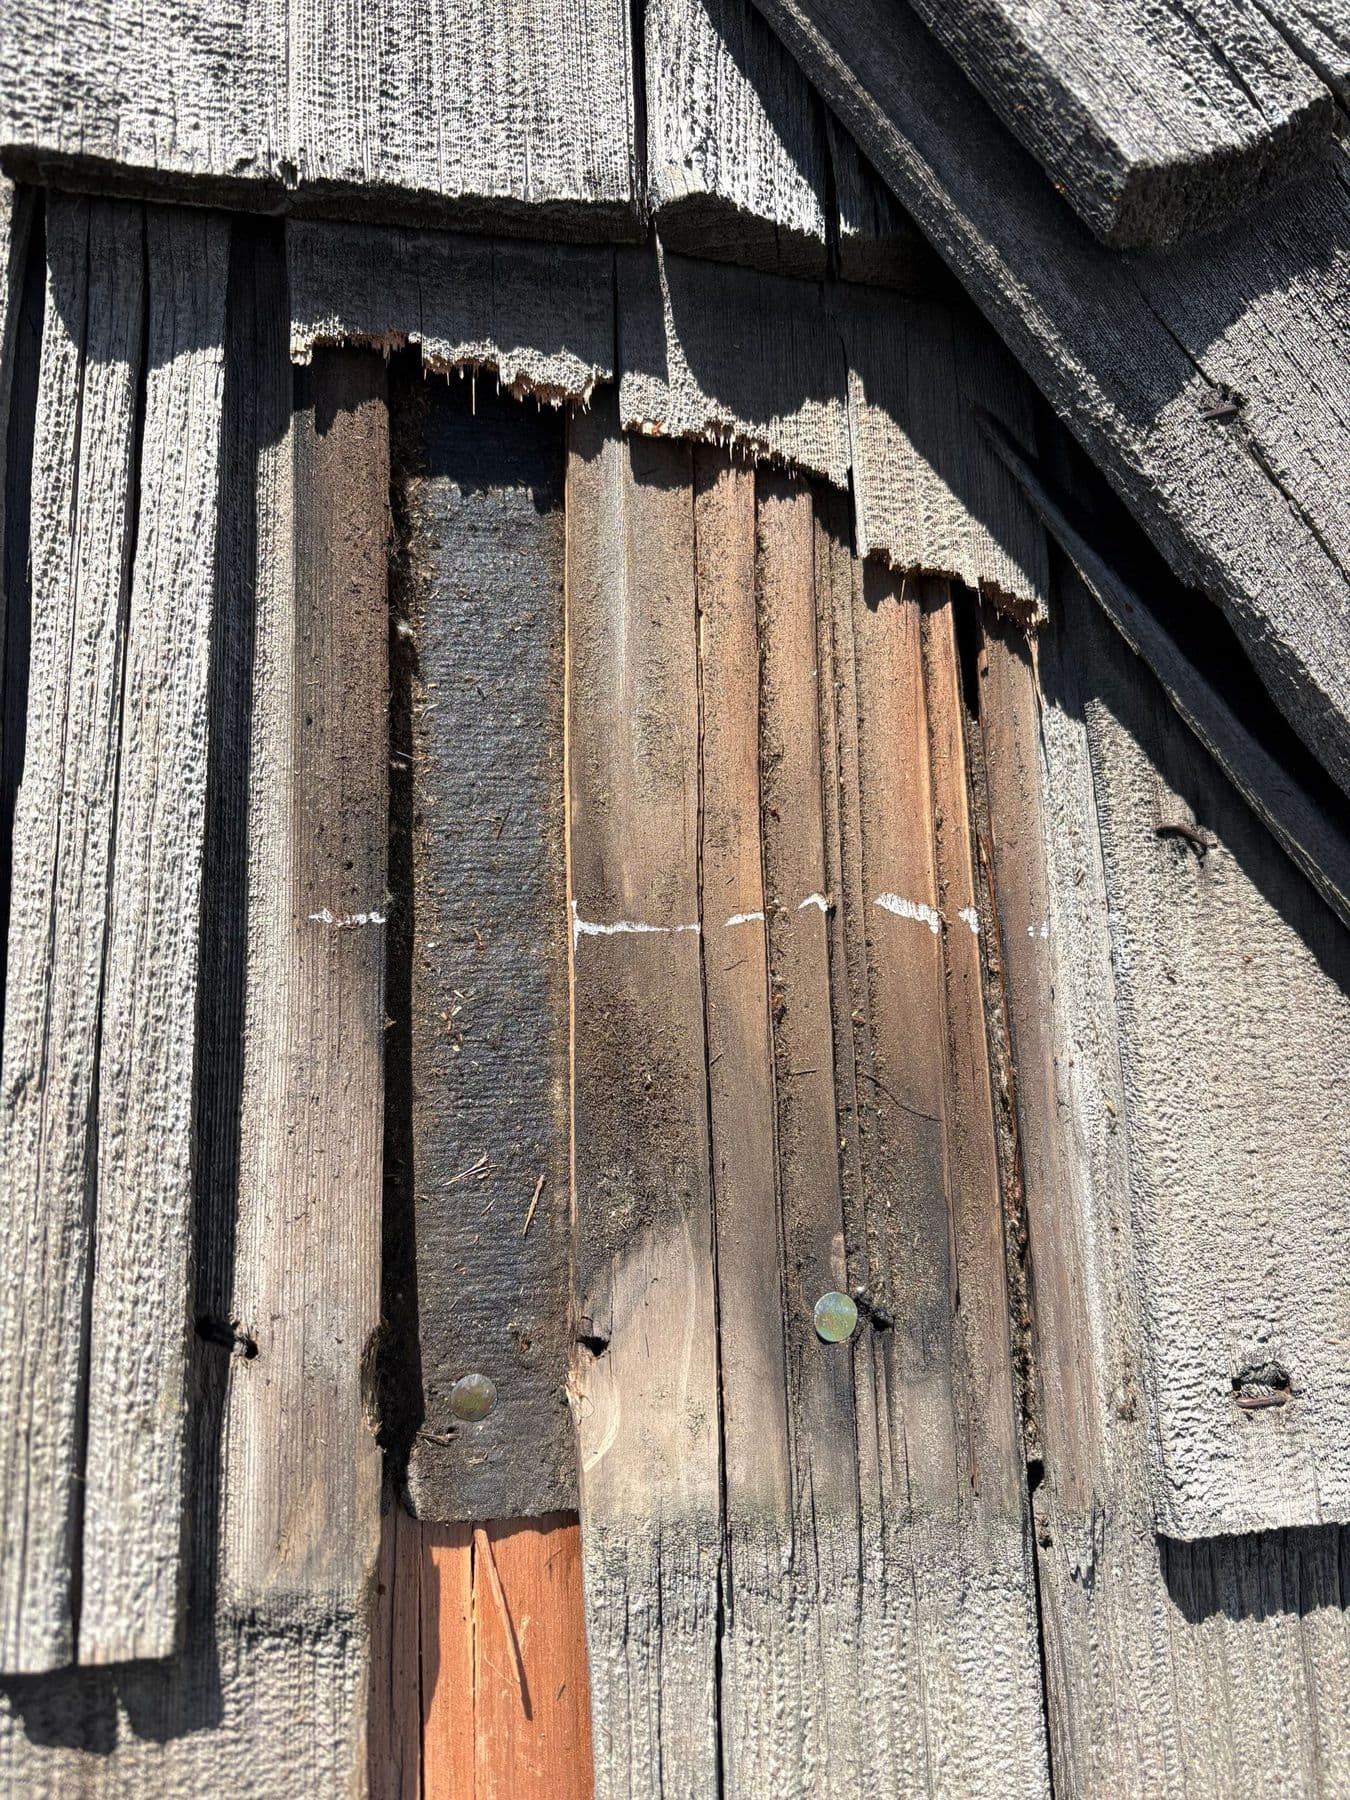
The shake above the repair cracks down its length 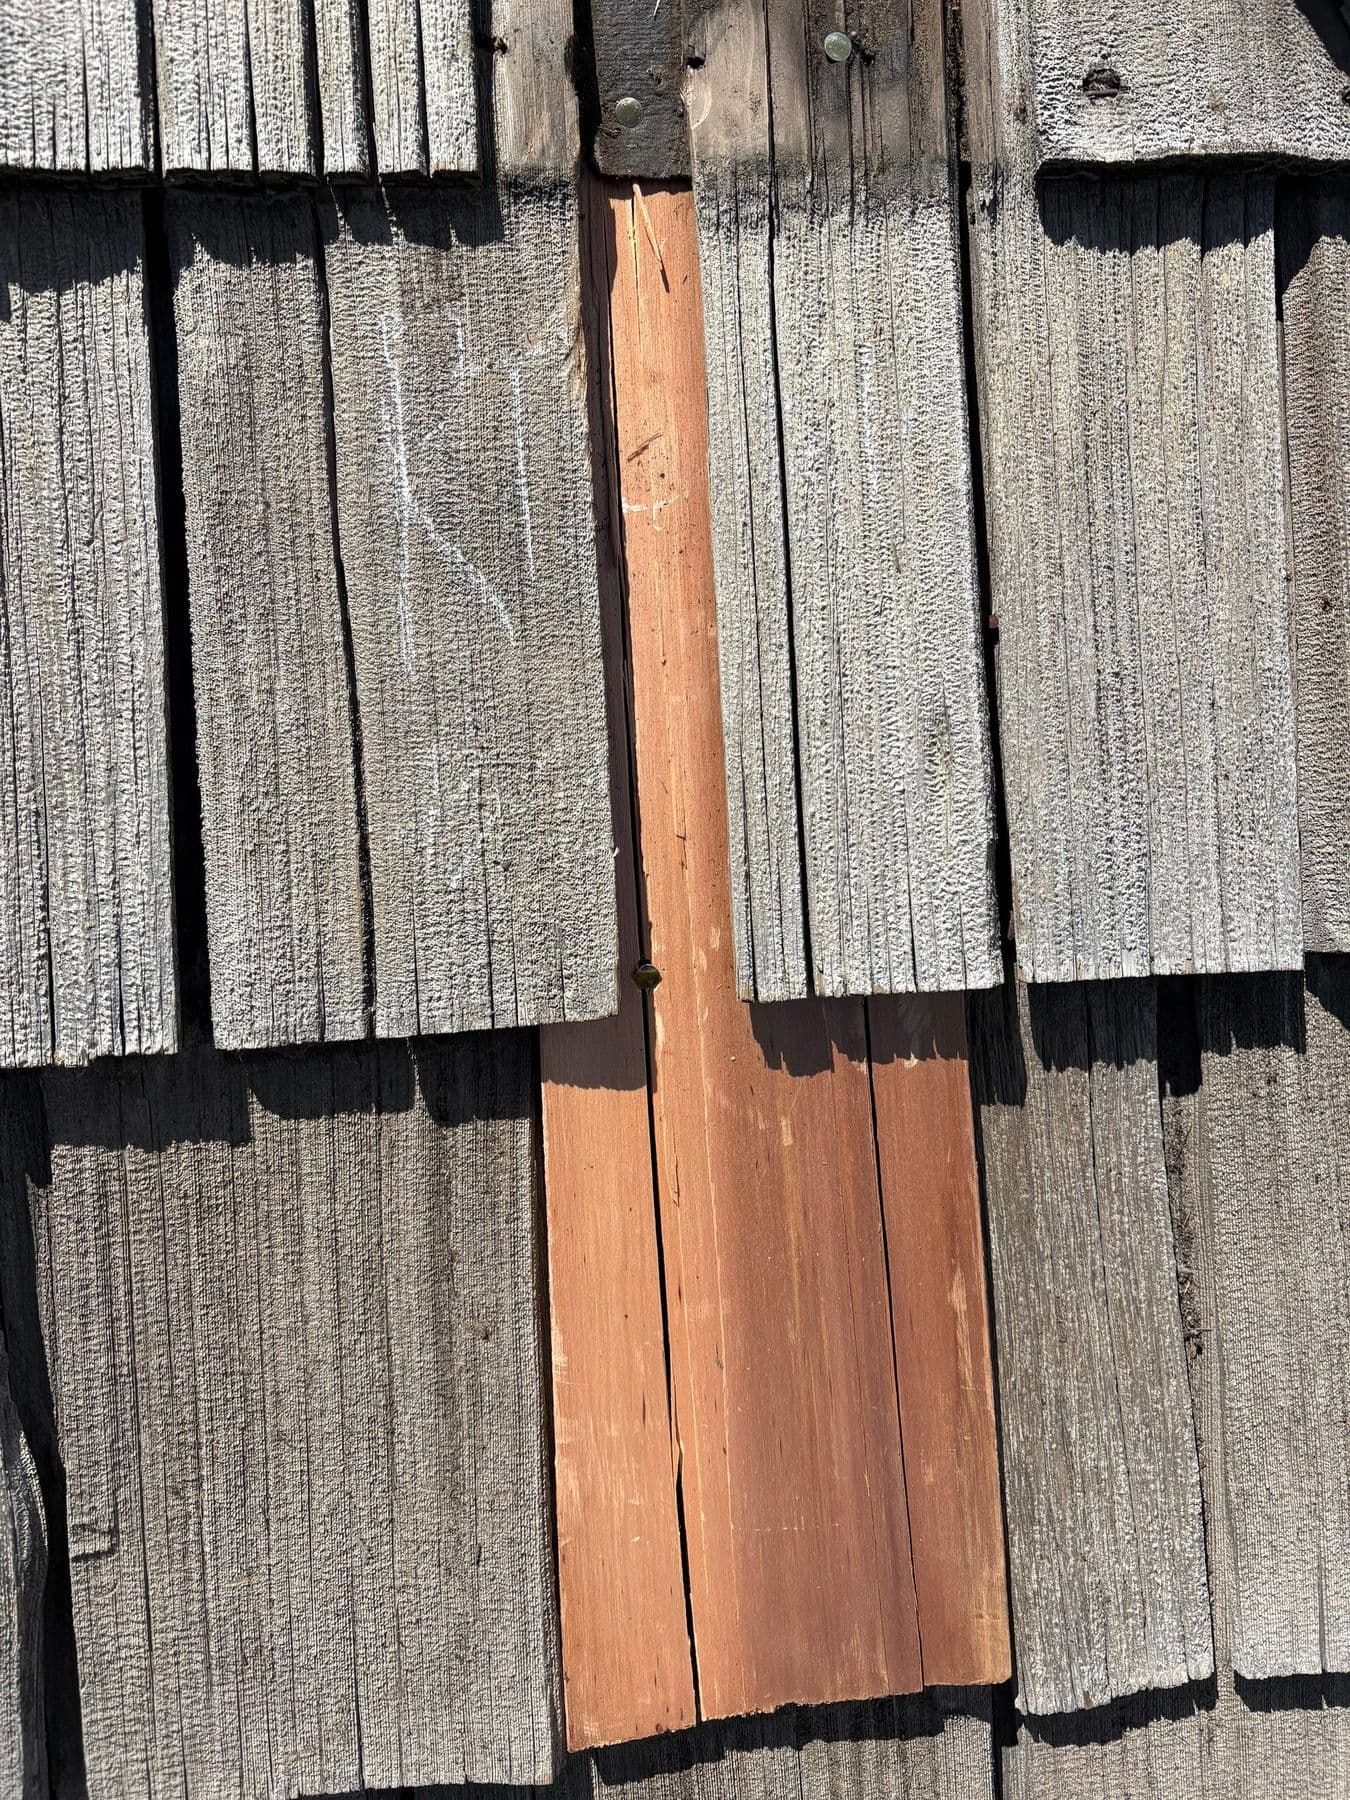
One new shake in. The course above it is already broken 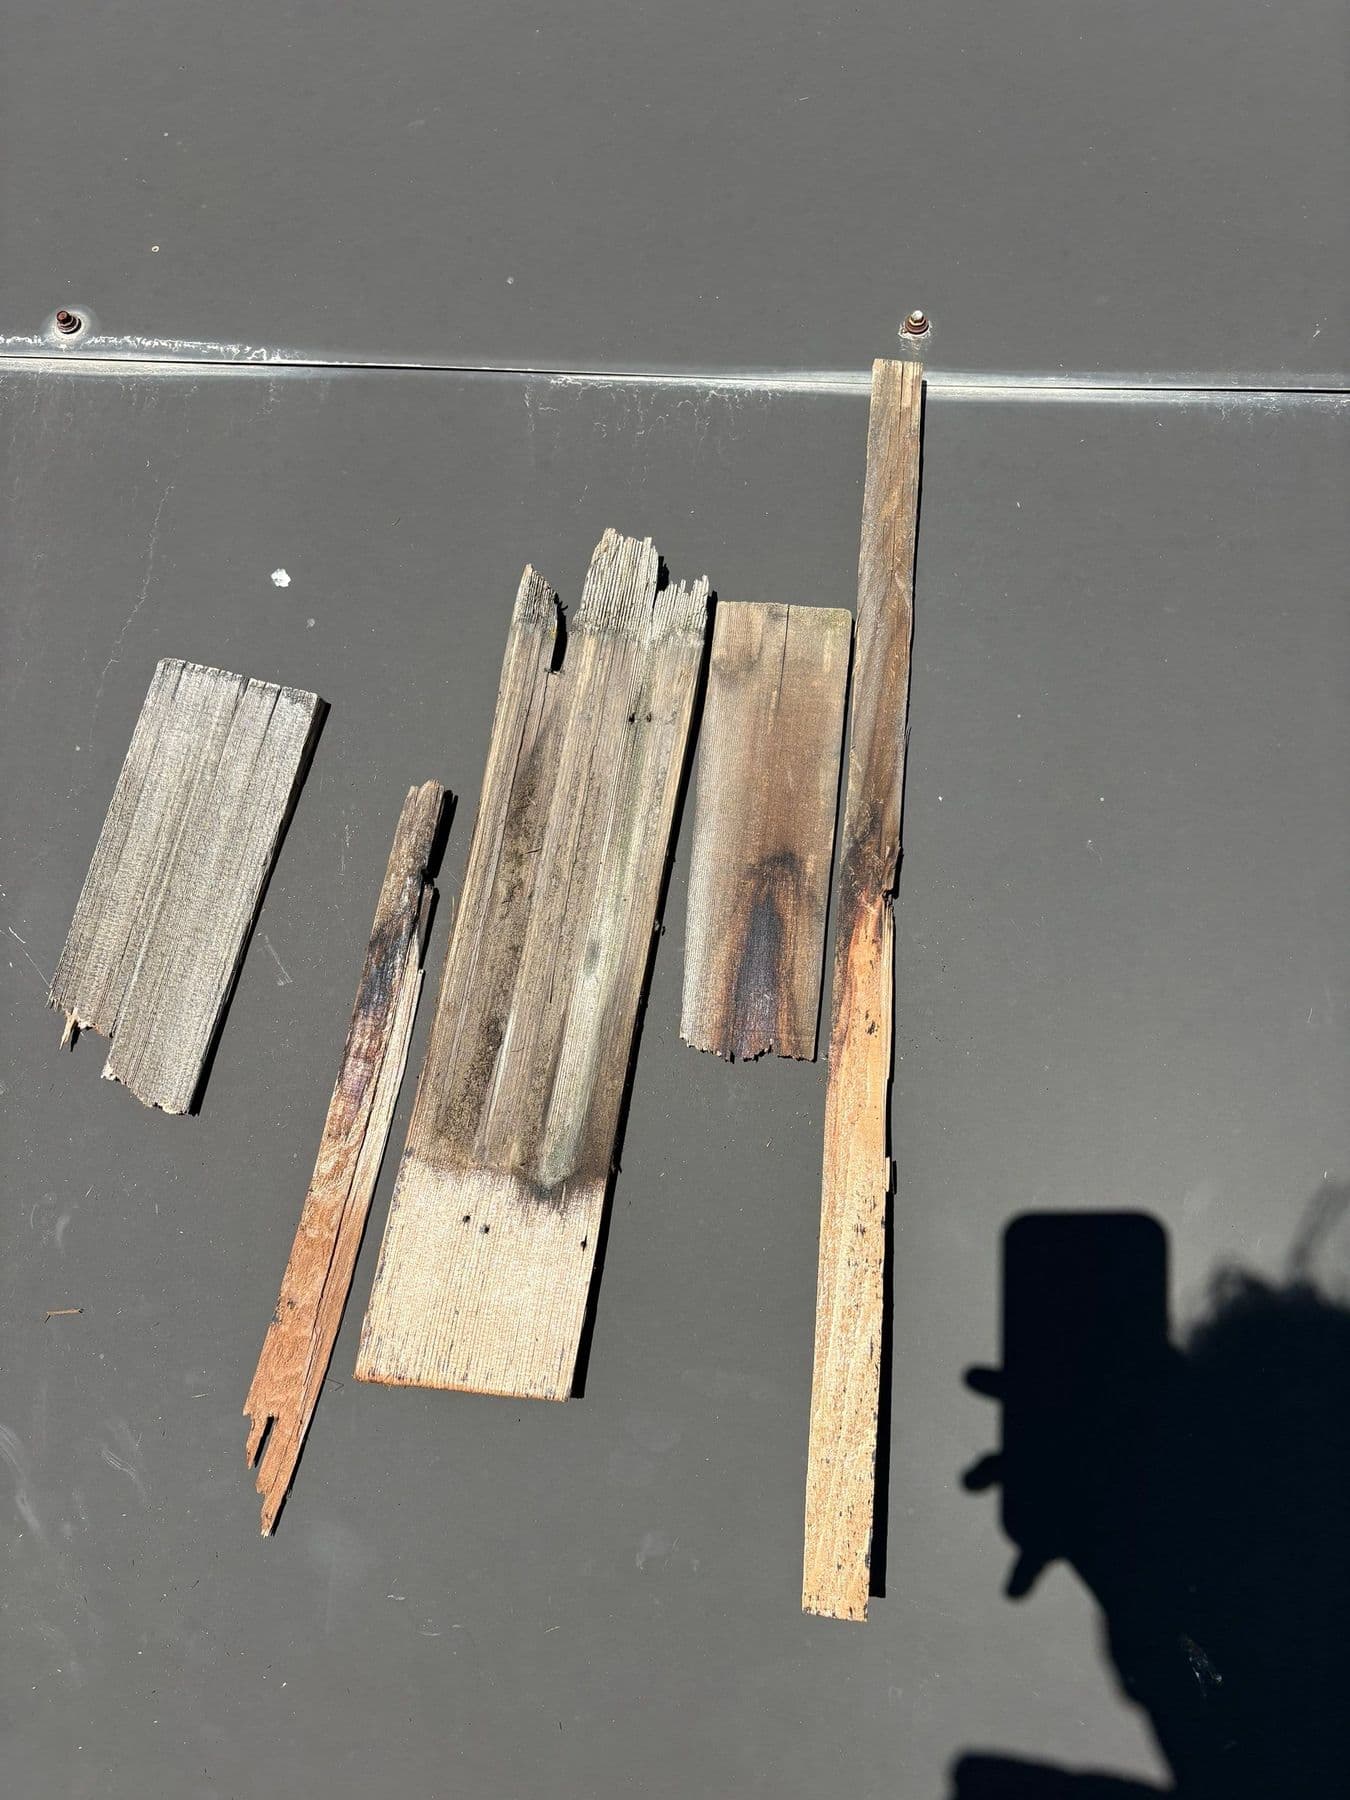
What came off to replace a single shake 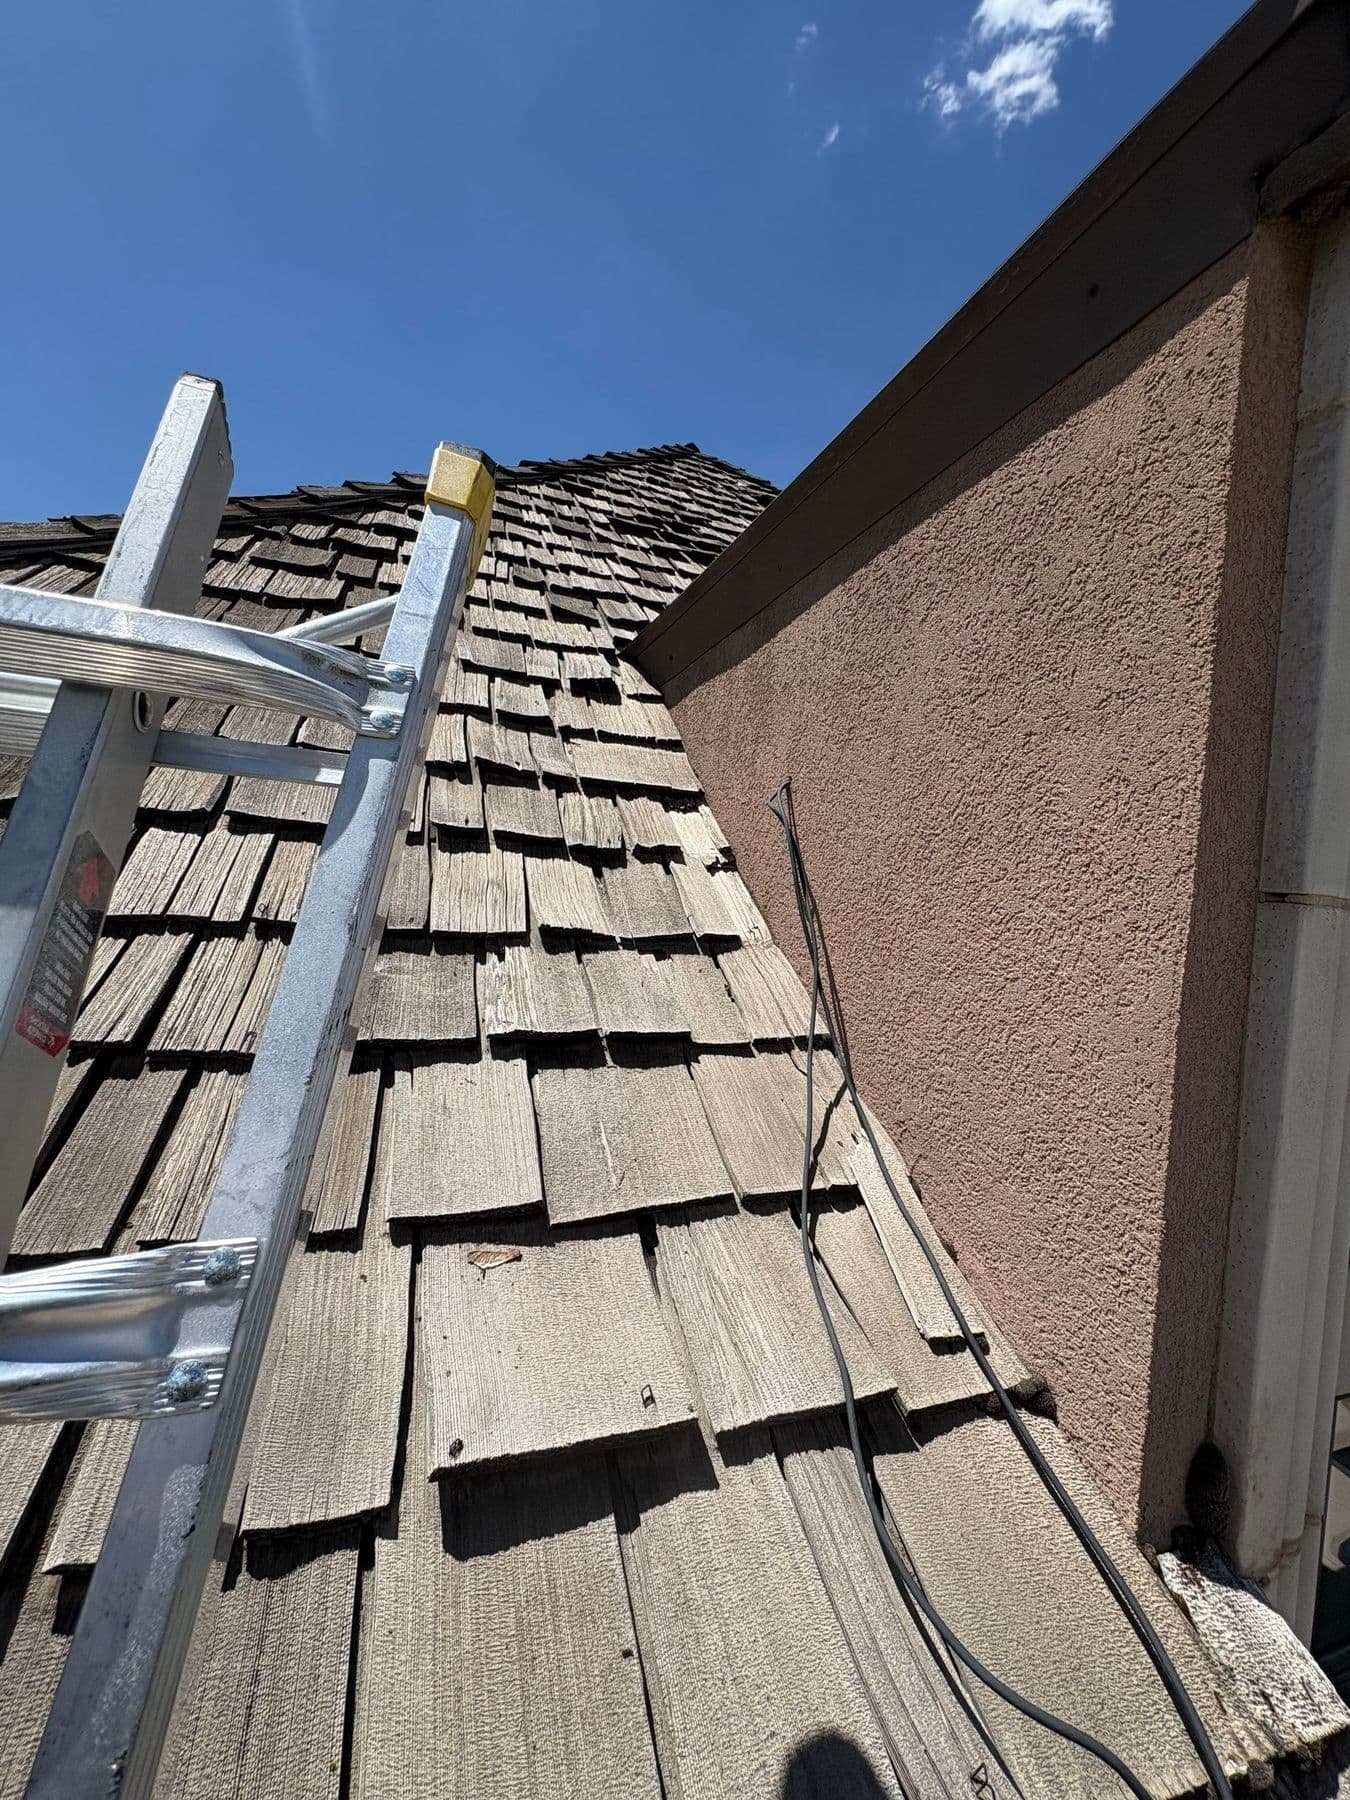
Two stories up at 10/12 pitch. Every repair means walking on it The video couldn't be emailed at full quality, and the insurance company had no upload portal for it, so we posted it as a private link and sent that on June 9.
07 · June 19
Claim closed
Insurance company · Jun 19
Your video indicates a repair on a slope. The wind damage to the roof was on the hip and ridge. There was no damage found on the slopes. Our position remains the same. The claim has been closed.
This is the point where most claims end. The homeowner gets a closing letter, figures the insurance company knows best, and either lives with the roof or pays for it. We wrote back the same day.
08 · June 19 to July 10
The rebuttal
We made three arguments, in writing, with evidence attached to each.
Their own estimate disagreed with them
In April the insurance company revised its estimate to replace 50 shakes. Those shakes were on the slopes. In June it said no slope damage was found. We put the two statements side by side.
Utah law counts what breaks during a repair
Utah Admin. Code R590-190-13(1)(a) says damage caused while making a covered repair is part of the loss. Our video showed every repaired shake breaking the ones above it.
The math on a single slope
Slope S15 had 12 damaged shakes. Each repair has to be woven up course by course to the ridge. That means replacing about 6 of the slope's 8 squares one shake at a time, which costs more than replacing the slope.
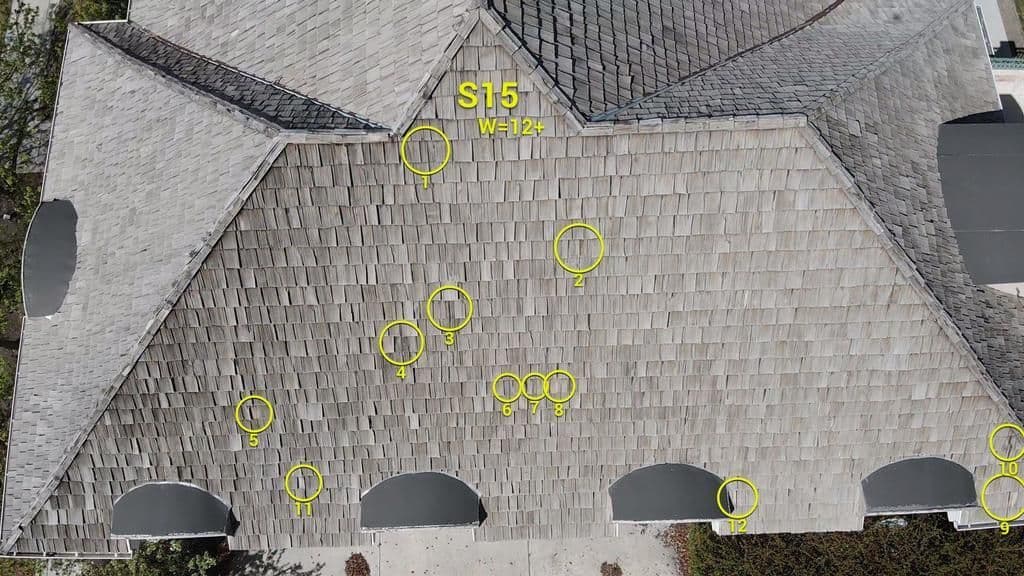 S15: 12 damaged shakesEvery repair runs to the ridge
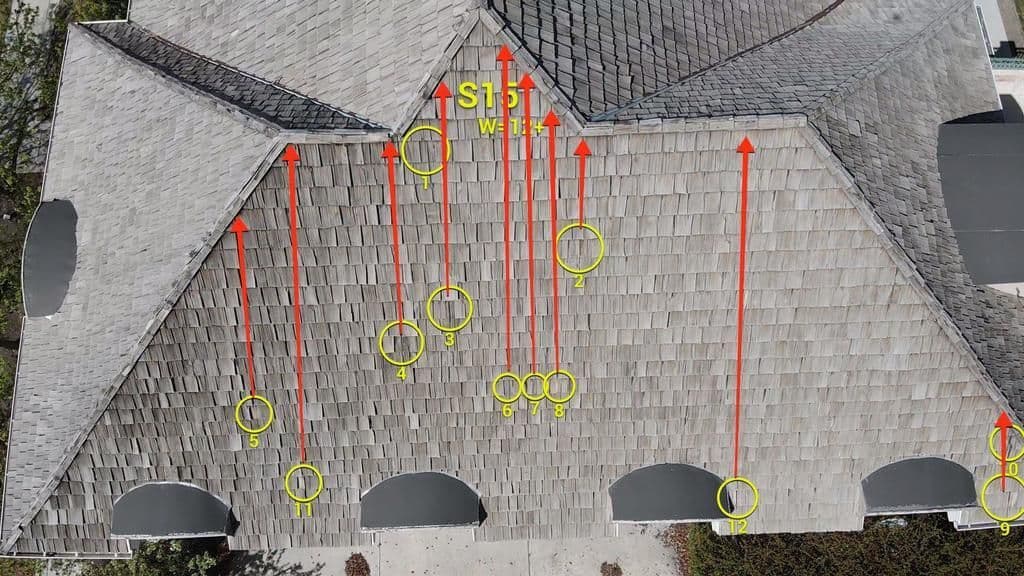
Slope S15, the one we used as the example. Keep scrolling and the arrows show how far each individual repair has to climb. We also pointed out that the insurance company's own per-shake Xactimate line item is labeled “to be used only for minor spot damage.”
09 · July 20 to August 14
An engineer on the roof
On July 20 the insurance company hired a forensic engineering firm to look at repairability. Two weeks later nothing had moved, so we called the engineering firm ourselves, found out the job was stuck waiting on budget approval, and pushed the insurance company to approve it. A different engineering firm was assigned the next day.
We met the engineer at the house on August 14 with a ladder and a drone. On the roof, the engineer agreed there was wind damage and that the shakes weren't in repairable condition, and added that just walking on them to make repairs would crack more.
10 · September 1 to 21
Approved
On September 1 the homeowner got the call: full replacement. The insurance company asked us for a cost estimate for real cedar, so we wrote one line by line. Class B fire-treated tapersawn shakes, stainless steel nails and felt interlay per the Cedar Shake & Shingle Bureau manual, five chimneys, steep and two-story charges, and a Provo permit with three inspections.
Final approved amount
$279,824
- Roof size
- 107 squares
- Per square
- $2,615
- Homeowner's deductible
- $13,465
Big claims are paid in stages. The first check is the roof's depreciated value (plus code upgrades). The rest, the “recoverable depreciation,” is released once the new roof is on and photographed. When the homeowner texted us the first check asking if that was everything, this is what we walked them through.
What a cedar roof actually costs
Most people assume a shake roof costs about the same as a shingle roof. It doesn't come close. Each shake is only 4 to 6 inches wide and takes two stainless nails, every course is laid by hand on a steep pitch, and the underlayment is different. Here is the same roof priced both ways.
That's why getting a shake claim right matters so much. On this roof, the gap between the first estimate and the right one was more than $278,000.
This roof, 136 squares with waste
Architectural asphalt
≈ $82,700
about $608 per square
Cedar shake, as approved
$279,824
about $2,058 per square
About 3.4× the price of asphalt, square for square.
Asphalt figure is the median price per square across 240 of our insurance asphalt roofs in Utah, applied to this roof's size. Cedar figure is the insurance company's final approved replacement cost. A square is 100 square feet of roof.
What happens now
The money was approved at real-cedar pricing, and the homeowner can put it toward whatever they choose. We've brought them cedar samples and synthetic shakes built to look like cedar (CeDUR, DaVinci, and Brava), plus addresses of roofs we've finished in each so they can see them in person. Once they pick, we pull the permit and schedule the crew. We'll add the finished roof here when it's done.
What the homeowner didn't have to do
- 2repair tests on video
- 19slopes mapped by drone
- 50damaged shakes circled
- 2written rebuttals
- 1engineer on the roof
Plus every email, follow-up call, and status check with the insurance company in between.
Got a letter that says “below deductible”?
That letter isn't always the last word. We'll look at your roof and your estimate for free and tell you honestly whether there's more to fight for.
Details changed or left out to protect the homeowner's privacy. Dollar figures are from the insurance company's estimates and final approval.